
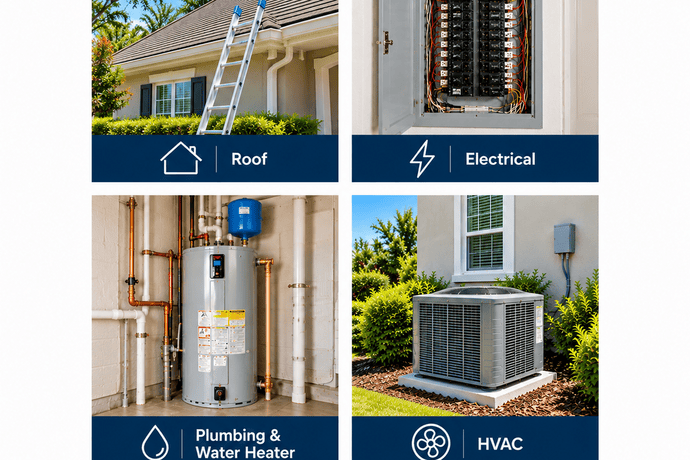
A 4-point inspection is commonly used in Florida during the homeowners insurance process. The inspection provides information about four major systems in a home: the roof, electrical, plumbing, and heating and air conditioning systems.
For Florida homeowners, understanding what a 4-point inspection looks for—and how insurance companies may use the information—can make the insurance quoting process easier.
What Is a 4-Point Inspection?
A 4-point inspection is a limited inspection that focuses on four major components of a home. It is different from a comprehensive home inspection because its primary purpose is to document the age, type, and general condition of specific systems that may be relevant to an insurance company's underwriting process.
The four areas typically reviewed are:
- Roof
- Electrical system
- Plumbing system
- Heating, ventilation, and air conditioning (HVAC) system
What Does a Florida 4-Point Inspection Look For?
Roof
The inspector may document the roof covering, approximate age, general condition, roof shape, and evidence of deterioration or damage. The report may also include an estimate of the roof's remaining useful life.
Electrical System
The inspection may document the electrical service, panel, wiring type, amperage, and other visible components. The inspector may also identify conditions that could require additional evaluation or repairs.
Plumbing System
The inspector may document the type of plumbing supply and drain materials, the approximate age of the system, the water heater, and visible signs of leaks or deterioration.
HVAC System
The inspection may document the type, age, and general condition of the home's heating and air conditioning equipment and whether the system appears to be functioning.
Why Do Insurance Companies Request a 4-Point Inspection?
Insurance companies may request a 4-point inspection to obtain additional information about a home's major systems when evaluating the property for homeowners insurance.
The age of the home, age and condition of its systems, previous updates, and an insurance company's underwriting requirements may influence whether an inspection is requested.
Requirements vary by insurance company. A 4-point inspection does not automatically determine whether a home will qualify for coverage.
How Is a 4-Point Inspection Different From a Wind Mitigation Inspection?
A 4-point inspection and a wind mitigation inspection serve different purposes.
A 4-point inspection focuses primarily on the roof, electrical, plumbing, and HVAC systems.
A wind mitigation inspection documents construction features that may help a home resist damage from high winds and hurricanes, such as roof-to-wall connections, roof shape, roof deck attachment, and protection for windows and other openings.
Depending on the home and the insurance company, a homeowner may be asked to provide one or both inspections.
What Happens If the Inspection Identifies a Problem?
If an inspection identifies an issue, the insurance company may request additional information, documentation, repairs, or further evaluation before determining whether the property meets its underwriting requirements.
The response will depend on the specific condition identified and the insurance company's current guidelines. Homeowners should discuss any inspection findings with their licensed insurance professional before assuming that a particular condition will prevent them from obtaining coverage.
When Should You Consider Getting a 4-Point Inspection?
You may want to discuss a 4-point inspection with your insurance advisor when purchasing an older home, shopping for homeowners insurance, changing insurance companies, or when an insurance company requests updated information about the property.
If you already have a recent 4-point inspection, keep a copy available when requesting homeowners insurance quotes.
4-Point Inspections and Florida Homeowners Insurance
A 4-point inspection is only one part of the homeowners insurance process. Insurance companies may also consider factors such as the age and condition of the home, roof characteristics, prior claims, location, construction type, and other underwriting information.
Insurance Scout Partners works with Florida homeowners to compare coverage options from multiple insurance companies and identify the information that may be needed during the quoting process.
Need Help With Your Florida Homeowners Insurance?
If you're buying a home, reviewing your current coverage, or trying to understand an inspection requirement, our licensed advisors can help you compare available homeowners insurance options.
Learn more about our Florida Homeowners Insurance options or contact Insurance Scout Partners for assistance.
Visit our Florida Insurance Knowledge Center for more guides about protecting your Florida home and understanding your insurance options.
Related Florida Insurance Guides
- Florida Wind Mitigation Inspection Guide
- Understanding Hurricane Deductibles in Florida
- How Does Your Roof Affect Homeowners Insurance in Florida?
- Replacement Cost vs. Actual Cash Value